Understanding Commercial Asset Investigation for Business Fraud Cases
Fraud concerns rarely appear all at once. They surface through inconsistencies, unexplained changes, and financial behavior that no longer adds up. Businesses reach a breaking point when assumptions stop working, and answers become necessary. Asset investigation for business fraud cases provides a way to see what is actually happening beneath the surface. Ownership, control, and movement tell a clearer story than explanations alone. That story determines how confidently a business can act when the consequences matter.
What Are Commercial Asset Investigations & What Is Their Purpose?
A commercial asset investigation is a structured process for understanding what a business truly owns or controls. It goes beyond financial statements to identify assets connected to disputes, misconduct, or deceptive activity.
This work is common when reported performance conflicts with observed behavior or contractual expectations.
In a commercial asset investigation for fraud cases, the objective is factual clarity rather than assumptions or speculation. Results support sound decisions by revealing ownership, control, and value across related entities.
Businesses use these findings to plan recovery, assess risk, and prepare credible legal strategies.
Why Financial Evidence Matters When Fraud Concerns Arise
When fraud concerns arise, businesses must determine whether suspicion reflects error, negligence, or intentional misconduct.
Financial evidence provides the framework needed to evaluate those concerns objectively. It shifts the conversation from perception to proof by showing how value moved, who controlled it, and when irregularities occurred.
Financial evidence matters in fraud situations because it allows businesses to:
- Establish factual timelines that show when assets were transferred, altered, or removed.
- Identify control and benefit by linking assets and transactions to specific individuals or entities.
- Separate intent from coincidence by analyzing patterns rather than isolated financial events.
Assess exposure accurately before pursuing asset recovery, litigation, or settlement discussions.
Support external review by providing documentation that investigators, attorneys, and insurers can rely on.
In asset investigation for business fraud cases, these elements work together to turn concern into actionable understanding. Without them, businesses risk making decisions based on incomplete or misleading information.
The Role of Asset Investigation for Business Fraud Cases
When a business suspects fraud, the priority is finding what changed and who controlled it. Asset work helps convert scattered red flags into a provable, business-ready picture.
When it comes to business fraud cases, the goal is practical clarity that supports decisive action. That clarity can shape recovery planning, negotiation posture, and legal options.
How Investigators Trace Misappropriated or Hidden Assets
Investigators start by mapping the people and entities who can come into contact with money or property. They build a timeline from invoices, payments, accounts, and key operational events.
Next, they compare normal activity against anomalies like sudden transfers or unexplained new vendors. They use ownership and filing records to connect related companies and potential proxy decision makers.
This process forms the basis of a hidden-asset investigation by revealing control paths that financial statements do not reveal.
They also verify hard assets through records tied to property, vehicles, and financed equipment. Financing and lien data can show what is owned versus what is heavily encumbered. For cash movement, investigators look for routing patterns across multiple accounts or counterparties.
The aim is to reconstruct the path of value, not guessing where it went.
Distinguishing Fraud-Focused Asset Reviews From Routine Financial Checks
Routine reviews test whether reporting appears accurate and consistent with standard accounting expectations. A fraud-focused review starts from a specific concern and tests competing explanations. It examines more transaction detail because small anomalies can reveal deliberate concealment. It also considers behavior signals, like timing around disputes or leadership changes.
A routine check may stop once the books balance and controls appear reasonable. A fraud review continues until the story behind the numbers becomes coherent and supported. It looks for relationships that do not belong, like shared addresses or circular payments.
The output is structured for action, not just internal accounting comfort.
Key Data Sources That Reveal a Business’s True Asset Picture
Reliable asset findings depend on combining multiple records that reflect ownership, control, and financial behavior. Each source offers a different perspective on how value exists or moves within a business environment.
When reviewed together, these records help confirm what is real versus what is reported.
#1) Public Filings and Corporate Ownership Records
Corporate filings provide insight into how a business is structured and who controls decision-making. They often reveal relationships that are not obvious from surface-level financial statements.
Ownership records help investigators understand where authority and benefit may converge.
Common records used include:
- Secretary of State filings that show officers, managers, and entity status
- UCC filings that identify pledged collateral and secured interests
- Litigation and lien records that signal financial pressure or disputes
In asset investigation for business fraud cases, these records often expose related entities or proxy ownership. They also help confirm whether reported operations align with legal and corporate reality.
#2) Property, Equipment, and High-Value Asset Verification
Tangible assets often represent the clearest expression of a business’s real economic position. Verifying these assets confirms whether the reported value reflects actual ownership or only appearance. Fraud cases frequently involve assets that are overstated, transferred quietly, or pledged without disclosure.
Verification focuses on confirming control, condition, and financial claims tied to physical assets. Ownership alone is not enough, since many assets are leased, financed, or shared across entities. Investigators examine records to understand how assets are held and who ultimately benefits.
Verification commonly involves reviewing:
- Real estate records connected to operating locations or investment holdings
- Vehicles, machinery, or equipment essential to revenue generation
- Financing agreements that reveal liens, collateral sharing, or hidden obligations
This analysis helps determine which assets remain available and which are already encumbered. It also highlights gaps between reported asset strength and operational reality.
In fraud matters, these gaps often signal misrepresentation or deliberate concealment.
#3) Banking Clues, Transfers, and Transaction-Level Patterns
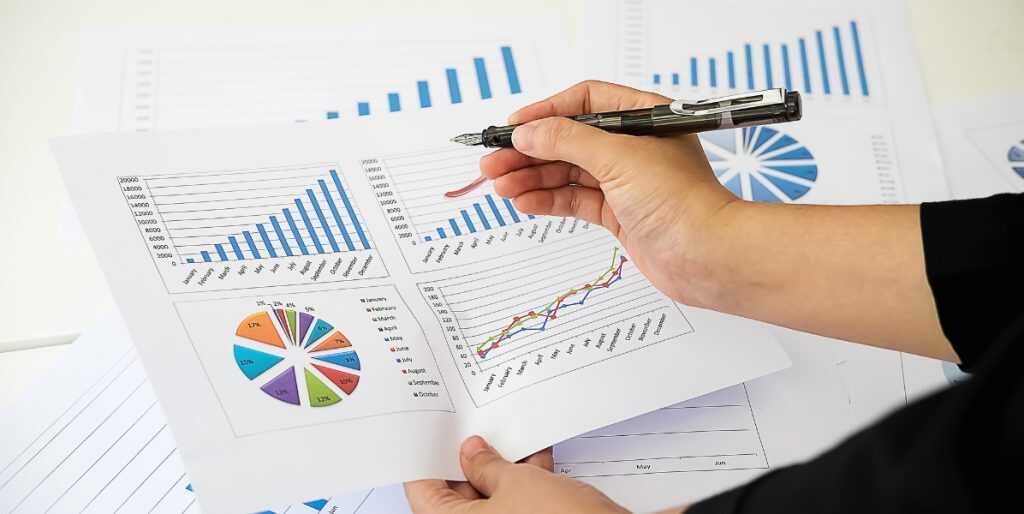
Banking activity provides a dynamic view of how a business actually moves and controls money. Unlike static filings, transaction behavior reflects real decisions made under pressure or intent. Reviewing this activity helps investigators understand whether funds followed expected operational paths.
Transaction analysis focuses on timing, frequency, and routing rather than isolated dollar amounts. Legitimate businesses tend to show consistent patterns tied to revenue cycles and expenses. Fraud concerns arise when activity shifts in ways that lack operational explanation.
Investigators commonly look for indicators such as:
- Transfers between accounts linked by ownership, shared addresses, or overlapping signatories
- Abrupt changes in payment destinations or cash flow routing without business justification
- Repeated transactions are structured to reduce visibility or delay detection
These indicators gain meaning when viewed together across time. In an asset investigation, patterns help reconstruct how value was redirected or concealed.
Methods Used in Commercial Asset Investigations
Effective asset work relies on disciplined analysis rather than isolated data points. Investigators apply structured techniques to connect records, behavior, and timing across related entities.
The methods emphasize consistency, verification, and documented reasoning that support defensible conclusions.
Following Digital Paper Trails in Complex Business Structures
Modern businesses leave extensive electronic records across vendors, platforms, and financial systems. Investigators follow these records to understand how decisions and transactions connect across entities. The goal is to establish continuity between actions, approvals, and outcomes.
Digital trails include invoices, contracts, payment records, and system logs tied to operations. When structures are complex, these records reveal coordination that simple ownership reviews miss. Consistent identifiers often link activity across subsidiaries or affiliates.
Investigators correlate dates, amounts, and counterparties to identify purposeful sequencing. They also assess whether the activity aligns with stated business functions.
Ultimately, coherence across records strengthens conclusions.
Identifying Layered Transfers Designed to Conceal Asset Movement
Concealment strategies often involve moving value through multiple steps to distance assets from their original source. Each step may appear routine on its own, but the sequence creates separation between control and visibility. Investigators evaluate the full chain rather than focusing on isolated transactions.
Layered movement becomes meaningful when activity lacks a clear operational explanation. Circular transfers, rapid pass-through accounts, or repeated use of intermediaries can signal intentional complexity. These patterns often emerge only when transactions are reviewed across time and entities.
Investigators assess whether layering serves a legitimate business function or merely obscures control. Timing around disputes, audits, or enforcement actions can further clarify intent. When economic rationale is absent, documented patterns support conclusions grounded in evidence rather than assumption.
Commercial asset investigations give businesses clarity when financial behavior no longer aligns with reported reality. Across evidence, sources, and methods, the work replaces suspicion with verified understanding and defensible conclusions.
Closing Thoughts: How Asset Investigation Findings Strengthen a Business Fraud Case
This perspective helps leaders assess exposure, regain leverage, and choose responses grounded in facts. When done correctly, asset investigation for business fraud cases turns complexity into direction. The lasting takeaway is readiness to act with confidence rather than react under uncertainty.
That readiness protects value, relationships, and credibility when the stakes are highest.
When clarity is required, we provide asset searches designed to identify and verify business-owned assets lawfully and accurately. This service directly supports the investigative approach outlined above by delivering evidence-ready insights for informed decisions.
For cases involving layered structures or higher complexity, our support services offer experienced guidance when deeper coordination and judgment are required.
Frequently Asked Questions
What Is Included in a Commercial Asset Investigation?
A commercial asset investigation includes identifying ownership, control, and financial interests tied to a business or related parties. It reviews public records, asset registrations, transactional behavior, and entity relationships.
The goal is to confirm what assets exist and how they are held. Findings focus on verified facts rather than estimates or assumptions. This information supports informed business, legal, or recovery decisions.
How Do Investigators Uncover Hidden Business Assets?
Hidden assets are uncovered by analyzing inconsistencies across records, behavior, and reported information. Investigators compare expected financial activity with observed transaction patterns and ownership links. They look for assets held through related entities or indirect control structures.
Timing, routing, and repeated activity often reveal deliberate concealment. Conclusions rely on documented connections rather than speculation.
How Long Does an Asset Investigation for Fraud Typically Take?
The timeline depends on complexity, data availability, and the number of entities involved. Simple reviews may take days, while complex matters can require weeks. Layered structures and incomplete records extend analysis time. Investigations prioritize accuracy over speed to avoid incorrect conclusions. Clear scope and objectives help streamline the process.